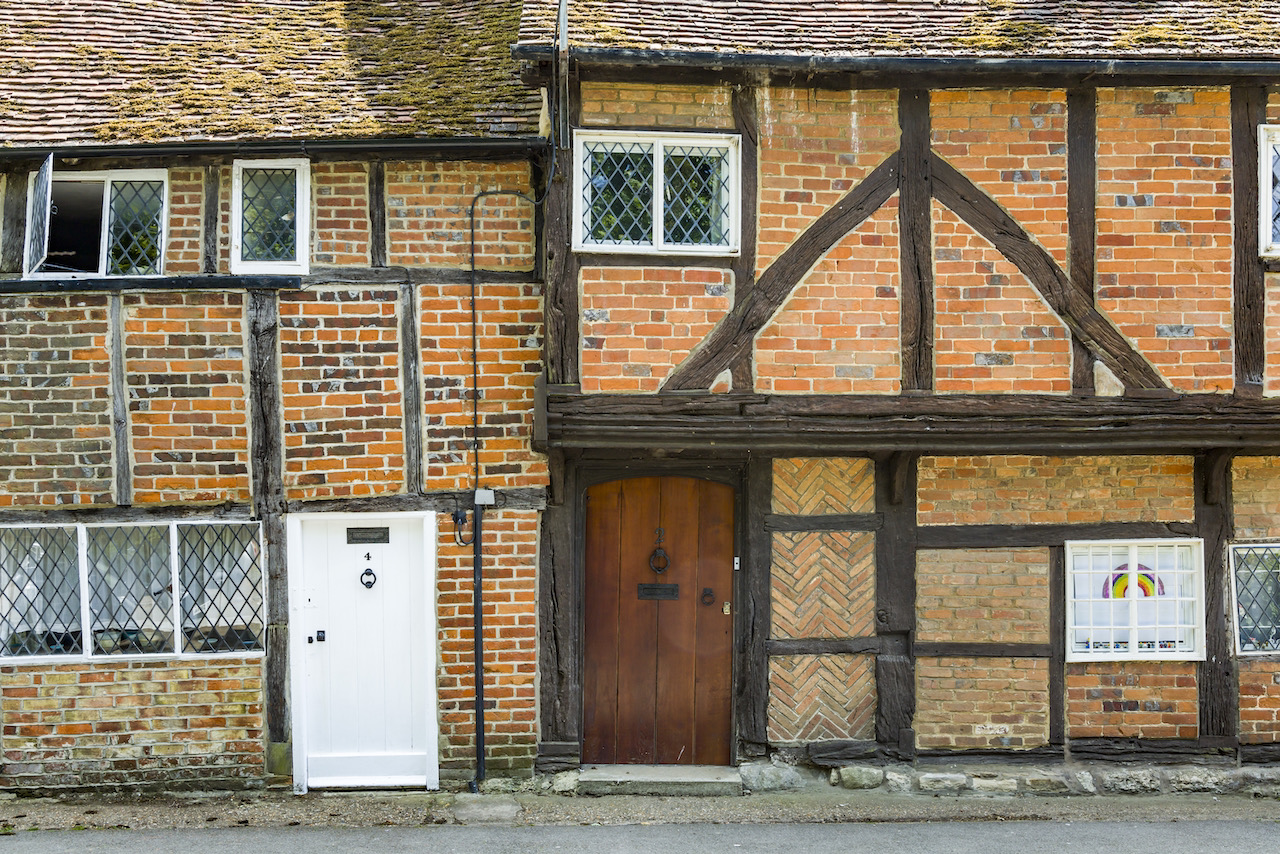
Specialist reinstatement
Consider traditional materials and skilled trades when assessing the rebuild value. The market value of the home is a different figure.
A home worth preserving.
Cover with the same care.
Insurance for listed homes with historic materials and individual character. We help you consider specialist repair costs, contents and the time it could take to put things right.
Personal advice · Mon–Fri, 9am – 5.30pm
A UK property insurance specialist, the same person every time. No phone menus.
01832 735388Authorised and regulated by the Financial Conduct Authority.
Firm Reference Number: 615253Listed building insurance is home insurance arranged with the property’s listed status, construction and specialist reinstatement needs in mind. The Home Insurer compares suitable policies from a limited panel, helping owners consider the cost of traditional materials, skilled labour and accommodation during insured repairs.
Consider traditional materials and skilled trades when assessing the rebuild value. The market value of the home is a different figure.
Check the alternative accommodation limit and duration. Specialist repairs can take time, particularly where materials or consents affect the programme.
Discuss contents and any higher-value possessions alongside the building, including item limits and cover away from home.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
A standard rebuild estimate may not capture all the features of a listed property. Specialist materials, access, professional fees and the complexity of the work can all matter. Discuss the valuation basis with us and consider a suitably qualified professional where the rebuild cost is uncertain. Tell us about proposed works before they begin.
Insurance responds to insured damage under the policy; it is not a general restoration or maintenance fund. Check the repair basis, limits, excesses and any conditions relating to the property’s condition or works.
Listed status is only part of the picture. Insurers also assess the rebuild value, construction, roof, location, occupancy, security and claims history. Compare the scope of specialist repairs and accommodation cover alongside the annual premium.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Head of Sales · The Home Insurer
Our listed-property team will ask about the building’s materials, history and listing. Share any valuation or survey you have, along with details of alterations, to help us discuss the right basis of cover.
Talk to our team on 01832 735388Read Tom’s bio →Something specific to your property?
Talk it through with us.
Yes. Tell us the exact listing designation and where in the UK the property is located, along with its construction and use. We can discuss suitable specialist options; listing systems and underwriting requirements vary.
Buildings insurance is normally based on the cost of reinstatement rather than the purchase price. A listed home’s specialist repair and rebuilding costs need careful consideration. Ask us what valuation information the insurer requires.
Do not assume it does. Disclose the planned works, value, duration and whether the property will be occupied. Renovation or works cover may be needed.
We can approach specialist insurers for homes that are both listed and thatched. Provide roof, heating, inspection and construction details so both features are considered.
The rebuild cost is what it would cost to rebuild your property from scratch, including demolition, VAT, site clearance and architects’ and surveyors’ fees. It is not the market value and not what you paid for it. For older, listed, thatched or stone-built properties it is often considerably higher than market value.
We must use the figure you give us. If it is too low, your insurer can reduce a claim in proportion — a 40% shortfall can mean 40% taken off any claim, including small ones. A £20,000 escape of water claim could pay out £12,000.
So that this doesn’t happen to you:
You can find a RICS-regulated surveyor in your area through the RICS directory at dir.rics.org. We don’t receive any payment from surveyors and we don’t have a panel — the choice of firm is entirely yours, and your contract will be with them.
If you’d rather talk it through first, call us on 01832 735388 and we’ll explain what to ask for.
Please review your rebuild cost at every renewal, and whenever you extend or alter the property.
More detail, with a worked example, in our rebuild cost guide.
Tell us about your property and we’ll help you understand the options available.
The Home Insurer is a trading style of Property Expert Limited, authorised and regulated by the Financial Conduct Authority under firm reference number 615253, and a member of the British Insurance Brokers' Association.
Under the FCA's Consumer Duty we are committed to fair-value policies you can depend upon when you need them, and to good outcomes for every customer.
We place cover through a panel that includes Lloyd's of London markets, and we tell you which insurer we have recommended and why before you buy.