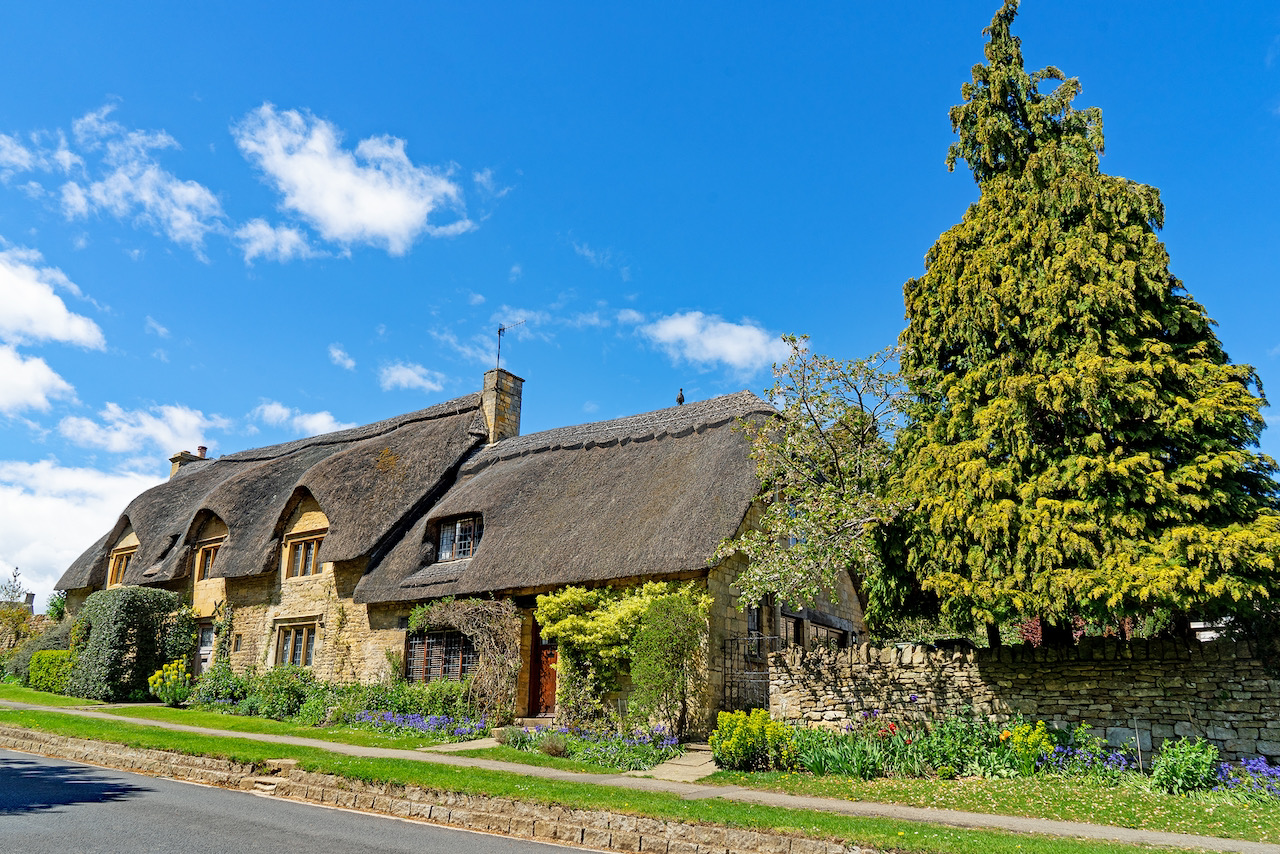
Your building & roof
Discuss the rebuild value, thatching materials, wall construction and any listed status so the quotation reflects the home you actually own.
A home with character.
Cover that understands it.
Specialist insurance for thatched cottages, listed thatch and homes with unusual construction, placed with underwriters including Hadron, Aviva and Beazley. We take the time to understand your roof, your heating and the way you live.
Personal advice · Mon–Fri, 9am – 5.30pm
A UK property insurance specialist, the same person every time. No phone menus.
01832 735388Authorised and regulated by the Financial Conduct Authority.
Firm Reference Number: 615253Thatched home insurance covers a thatched building and, when selected, its contents against insured events. The Home Insurer is a UK specialist broker, trading since 2016 and arranging thatched home insurance since 2019. We have developed our own thatch scheme with Quintus Underwriting, and we also compare policies from a panel of insurers including Hadron, Aviva and Beazley, with particular attention to fire precautions, roof condition and the cost of specialist repairs.
Discuss the rebuild value, thatching materials, wall construction and any listed status so the quotation reflects the home you actually own.
Ask about contents, valuables and possessions away from home. These are separate choices, with their own limits and conditions.
Tell us about holiday use, letting, an empty period, renovation work, flooding or previous subsidence. Each needs to be disclosed and agreed.
Cover is subject to underwriting, policy terms, limits, conditions and exclusions. Your quotation and policy documents confirm what is included.
A solid-fuel stove or open fire needs careful assessment. Insurers can set conditions for chimney height, sweeping, lining and maintenance. Tell us exactly what is installed and how it is used; do not assume another owner’s requirements apply to your property. We will explain the requirements in your quotation, including any reports needed before or after cover starts.
Routine maintenance, wear and tear and replacing an ageing roof are different from damage caused by an insured event. Check the schedule for fire conditions, excesses, exclusions and any deadline for supplying inspection reports.
These are the conditions we see most often. Every insurer sets its own, and the ones that apply to you are listed in your quotation.
| Condition | Typical requirement |
|---|---|
| Chimney height | A flue serving a wood burner or open fire should finish at least 1.8 m above the thatch and at least 2.3 m from it measured horizontally, in line with Building Regulations Approved Document J. |
| Chimney sweeping | Typically at least twice a year when burning wood. Keep the dated certificates from a registered sweep. |
| Flue lining | A sound, lined flue is normally required for a solid-fuel stove. Some insurers specify an insulated stainless steel liner. |
| Electrical inspection | An electrical installation condition report (EICR) is commonly required, often no more than five years old. |
| Fire protection | Heat or smoke detection in the roof space, fire-retardant barrier boards or treatment. Some insurers ask for these; others take them into account. |
| Thatch type | Typical life of the coat |
|---|---|
| Water reed | 25 to 40 years or more |
| Combed wheat reed | 25 to 40 years |
| Long straw | 15 to 25 years |
| Ridge (any type) | Replaced every 10 to 15 years |
Insurers are mainly interested in the condition and age of the coat and when it was last ridged, rather than the material itself. Tell us all three.
As a guide: thatched home premiums we arrange start from around £550 a year, and the average is around £1,000 (October 2026).
The biggest influences are usually the rebuild value, whether there is a wood burner or open fire, and the age and condition of the thatch. Location, wall construction, occupancy and claims history also count. Comparing the premium alongside fire conditions, excesses and contents limits gives a more useful result than comparing price alone.
Send us your renewal terms if you have them. We can compare the cover, excesses and conditions with the options available through our panel and explain our recommendation.
Head of Sales · The Home Insurer
Our thatch team will talk through the details of your home and explain the conditions attached to the recommended policy. Have your roof and electrical inspection reports to hand if you have them.
Talk to our team on 01832 735388Read Tom’s bio →Something specific to your property?
Talk it through with us.
Yes. We arrange cover for Grade I, II* and II listed thatched homes, including cob, timber-frame and stone construction, through specialist insurers on our panel. Tell us the listing grade, how the home is built and any repairs or alterations you’re planning. Whether the insurer accepts the home, and on what terms, depends on the property. Listed repairs usually need matching materials and traditional craftspeople, so your rebuild figure should reflect that.
Yes. Many of our insurers cover thatched homes with a wood burner or open fire, as long as the installation and upkeep meet their requirements. We’ll ask about:
Some insurers set conditions on using the stove. We’ll tell you what they are before you buy.
Your most recent thatch condition report and electrical installation condition report (EICR). Insurers typically want an EICR from within the last five years and may ask for proof that any recommended repairs have been done. If your reports are out of date, call us anyway. We’ll tell you what each insurer needs before you book inspections.
Usually, yes. Flood is normally part of standard buildings and contents cover, but insurers may exclude it, restrict it or apply a higher excess where a home has flooded before or is in a high-risk area, so check each quotation. If your home has a flood history or known risk, tell us and we’ll check whether a Flood Re-backed policy is available. Being built before 2009 does not on its own make a home eligible.
As a guide, thatched home premiums we arrange start from around £550 a year, and the average is around £1,000 (October 2026). Your own premium depends mainly on the rebuild value, whether there is a wood burner or open fire, the age and condition of the thatch, and the cover you choose.
Thatch is more combustible than tile or slate, fires in thatch are harder to put out, and rebuilding needs specialist materials and craftspeople. Premiums mainly depend on the rebuild cost, the heating type, how the thatch is kept up and your claims history. A specialist broker can often find better terms than a standard insurer.
Not routine rethatching. Thatch wearing out over time is treated as maintenance. Damage from an insured event, such as fire or storm, is normally covered, subject to the policy terms. We’ll point out any exclusions before you buy.
Not usually. Most insurers do not require one, and fire services generally advise against spark arrestors on wood burners because they clog with soot and tar. If your insurer does require one, it must be cleaned regularly. Your quotation will state your insurer’s position.
Yes. Tell us how often it’s let or empty and who uses it. Some insurers treat holiday lets as commercial risks, so the cover and price can differ from a main-residence policy.
The rebuild cost is what it would cost to rebuild your property from scratch, including demolition, VAT, site clearance and architects’ and surveyors’ fees. It is not the market value and not what you paid for it. For older, listed, thatched or stone-built properties it is often considerably higher than market value.
We must use the figure you give us. If it is too low, your insurer can reduce a claim in proportion — a 40% shortfall can mean 40% taken off any claim, including small ones. A £20,000 escape of water claim could pay out £12,000.
So that this doesn’t happen to you:
You can find a RICS-regulated surveyor in your area through the RICS directory at dir.rics.org. We don’t receive any payment from surveyors and we don’t have a panel — the choice of firm is entirely yours, and your contract will be with them.
If you’d rather talk it through first, call us on 01832 735388 and we’ll explain what to ask for.
Please review your rebuild cost at every renewal, and whenever you extend or alter the property.
More detail, with a worked example, in our rebuild cost guide.
Tell us about your property and we’ll help you understand the options available.
The Home Insurer is a trading style of Property Expert Limited, authorised and regulated by the Financial Conduct Authority under firm reference number 615253, and a member of the British Insurance Brokers' Association.
Under the FCA's Consumer Duty we are committed to fair-value policies you can depend upon when you need them, and to good outcomes for every customer.
We place cover through a panel that includes Lloyd's of London markets, and we tell you which insurer we have recommended and why before you buy.